Written By: Flipbz.org
Greenwich Bank has commenced commercial banking operations in Nigeria, commissioning three branches in Ikoyi, Victoria Island and Surulere as it transitions from merchant banking into retail and SME territory long dominated by established giants, raising the question of whether physical branches still matter in an increasingly digital Nigerian banking market.
Nigeria's commercial banking market is not an easy one to walk into. It is dominated by institutions with decades of brand recognition, millions of existing customers, and sprawling digital platforms already embedded in everyday Nigerian life. A 30-year-old financial services group just decided that the opportunity to compete there was worth the risk.
What Happened
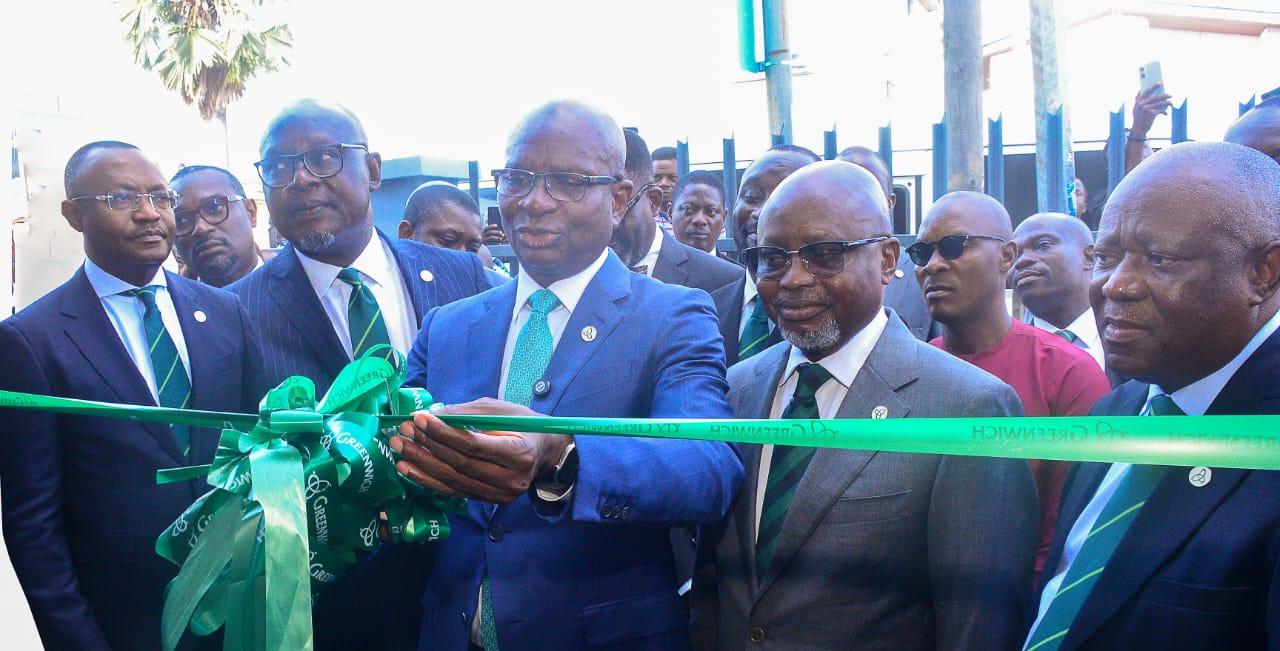
Greenwich Bank Limited has commenced operations as a regional commercial bank, commissioning three branches in Ikoyi, Victoria Island and Surulere, Lagos, on Friday, October 2, 2026, as it begins a new phase of expansion beyond merchant banking. The rollout is not stopping at three locations, since the bank is also scheduled to commission branches in Akure on October 8 and Ado-Ekiti on October 9, bringing the first phase of its commercial banking network to five locations.
The regulatory foundation for this expansion was laid just weeks earlier. The expansion follows regulatory approval granted in August 2026 for Greenwich to operate as a regional commercial bank, widening its mandate beyond traditional merchant banking to include individuals, small and medium-sized enterprises, commercial organisations and public-sector institutions. Lagos State lent early political weight to the launch, with Governor Babajide Sanwo-Olu, represented by the Commissioner for Finance, Abayomi Oluyomi, commissioning the bank's Awolowo Road, Ikoyi branch and saying Greenwich Bank had an important role to play in the economic development of the state.
From Merchant Bank to Commercial Bank: Why the License Upgrade Matters
To understand why this launch is significant, it helps to understand what Greenwich was before and what the new license actually unlocks. Greenwich Holdings Limited announced that its subsidiary, Greenwich Merchant Bank Limited, had received Approval-In-Principle from the Central Bank of Nigeria to convert into a regional commercial bank, a transition the Chairman described as reflecting years of disciplined execution and a clear strategic vision, marking the beginning of a broader mission to deepen financial access.
The practical difference between the old and new license is substantial. The new licence expands its services beyond traditional merchant banking to include retail customers, small and medium-sized enterprises, commercial organisations and public-sector institutions, a customer base merchant banks in Nigeria are generally not permitted to serve directly. Greenwich Bank Managing Director Benson Ogundeji framed the shift in terms of reach rather than just regulatory status, saying the transition significantly expands the Bank's ability to serve customers, allowing it to extend its services to a much wider spectrum of the economy.
A 30-Year Institutional History Behind a New Commercial Brand
Greenwich's entry into commercial banking is not the debut of a new or unproven institution, it is a licensing evolution for a financial services group with decades of operating history across adjacent businesses. Greenwich Holdings Limited represents a new chapter in the unparalleled growth that began with Greenwich Trust Limited, a foremost provider of financial solutions that commenced operations in June 1994 as a financial adviser and issuing house, later converting to Greenwich Merchant Bank Limited in 2020 after receiving CBN approval. Over its history, Greenwich expanded its footprint across various segments of the financial sector through subsidiaries and affiliated entities, including Greenwich Registrars and Data Solution Limited and Greenwich Trustees Limited, alongside asset management and securities businesses.
Chairman Kayode Falowo invoked that institutional depth directly at the Ikoyi commissioning, stating that commercial banking was the natural step for Greenwich to follow after all it had done, and that the bank would build on more than three decades of experience in stockbroking, issuing house services, investment banking and other financial services. The group's recent financial performance offers some indication of the base it is building from, with customer deposits increasing by 80.5 per cent to N173.84bn in the 2025 financial year, a growth rate Falowo attributed to prudent management, operational efficiency and strategic investments.
Why Physical Branches Still Matter, Even in a Digital-First Market
Greenwich's decision to lead its commercial banking debut with physical branch commissionings, rather than a purely digital rollout, is itself a notable strategic signal in a market where mobile-first and digital-only banks have proliferated. The bank has been explicit that branches are not meant to be the whole strategy, since Falowo added that the bank would leverage technology to serve customers beyond its physical branch locations, positioning the branches as anchors for trust and visibility rather than the sole channel for customer engagement.
That branch-plus-digital hybrid approach reflects a calculated bet about what a new entrant needs to establish credibility in Nigeria's commercial banking market, where incumbent banks have spent decades building both extensive branch networks and sophisticated digital platforms simultaneously. For a bank converting from a merchant banking background, where its historical customer base was built on the trust of large corporate relationships, physical branches in high-visibility Lagos commercial districts like Ikoyi and Victoria Island plausibly serve as a credibility signal to retail and SME customers who may be unfamiliar with the Greenwich name in a consumer banking context.
The Expansion Roadmap and National Ambitions
Greenwich's five-branch opening phase is explicitly described as just the beginning of a larger geographic rollout. The bank disclosed plans to open branches in Akure, Ondo State, and Ado-Ekiti, Ekiti State, with further expansion planned across the South-West, South-South and North-West regions, as well as the Federal Capital Territory. That expansion footprint is directly tied to the bank's specific regulatory authorization, since Falowo said the bank would establish additional branches in other locations within the regions approved by the Central Bank of Nigeria.
The regional license, however, is explicitly framed as a stepping stone rather than an end state. Greenwich said in a statement that it also plans to pursue a national banking licence in the medium term, with Falowo declaring at the Ikoyi commissioning: "I promise you and assure you that in a very few years, we will be coming again to celebrate a much bigger enterprise, which will be the national bank that is spread all over Nigeria."
Why It Matters
Greenwich's entry adds a new, institutionally established competitor into a segment of Nigerian commercial banking that has not seen frequent new entrants in recent years, particularly as the CBN's dramatically higher recapitalisation thresholds have made entering, or remaining in, commercial banking a far more capital-intensive proposition than in the past. That recapitalisation backdrop is directly relevant here, since Nigeria's revised minimum capital requirements, set at ₦500 billion for banks with international authorisation, ₦200 billion for national banks, and ₦50 billion for regional banks, have already reshaped the competitive landscape, making Greenwich's choice to launch specifically with a regional authorization a calculated first step rather than an attempt to compete immediately at national scale.
For Lagos and the South-West states where Greenwich's initial branches are concentrated, the expansion represents a tangible addition to local banking competition and employment, themes Lagos State's own government was quick to highlight in its public endorsement of the launch.
What Flipbz Thinks
Flipbz sees Greenwich Bank's launch as a useful test of whether institutional pedigree and a hybrid branch-digital strategy can carve out meaningful market share in a commercial banking sector where customer switching costs and incumbent brand loyalty remain significant barriers for new entrants. The decision to open in Ikoyi, Victoria Island, and Surulere, three of Lagos's most competitive and bank-dense commercial districts, suggests Greenwich is choosing to compete directly in incumbents' strongest territory rather than seeking underserved markets first, a bolder approach that will test its brand strength immediately rather than building a track record in lower-competition regions before scaling up. The more telling signal of long-term ambition is the explicitly stated national banking license goal, since regional authorization is a real but limited mandate, and how quickly Greenwich can build the deposit base and operational scale needed to credibly pursue that upgrade will be the clearest measure of whether this launch becomes a genuine growth story or remains a modest regional footprint.
What to Watch
Industry observers should watch how quickly Greenwich completes its planned branch rollout across the South-West, South-South, North-West, and FCT regions covered by its regional authorization, since the pace of that expansion will signal how aggressively the bank intends to compete for retail and SME deposits against established players. It will also be worth tracking how soon Greenwich formally applies for a national banking licence, and whether its deposit growth trajectory, which saw an 80.5% increase to ₦173.84 billion in 2025 under its merchant banking structure, continues at a comparable pace now that its customer base has expanded to include retail and SME segments.
The Bottom Line
Greenwich Bank's launch into commercial banking, backed by three decades of financial services experience and a hybrid strategy pairing physical branches with digital banking channels, represents a calculated bet that institutional trust and targeted regional expansion can carve out space in a commercial banking market dominated by long-established players. Whether Greenwich can translate its merchant banking pedigree into genuine retail and SME market share, and whether its stated ambition for a national banking license materializes on the timeline its chairman has promised, will determine if this becomes a notable new entrant story or a modest regional banking footnote.
Please register to comment.
With these components in place, your business...
SolidBase Builders Limited is a professionall...
PrimeStone Construction Nigeria Ltd is a well...
CrestRock Engineering Services Ltd is a scala...
Open the Listing model file located in the ap...
Discover promising partnership opportunities in various industries.
Pitch Your Startup | Find Partners
.jpeg)
.jpeg)
.jpg)

Comments